Pay Yourself First: రవి కథలో ఒక చిన్న Money Habit
“మిగిలినదాన్ని save చేస్తాను” అనే planలో, చాలా నెలలు మిగిలేది ఏమీ ఉండదు.
గమనిక: రవి, అతని కుటుంబం, shop—ఈ article కోసం సృష్టించిన fictional example. ఇది client case study కాదు; ఫలితాల హామీ కూడా కాదు.
నెలాఖరున రవి దగ్గర మిగిలింది… ప్రశ్న మాత్రమే
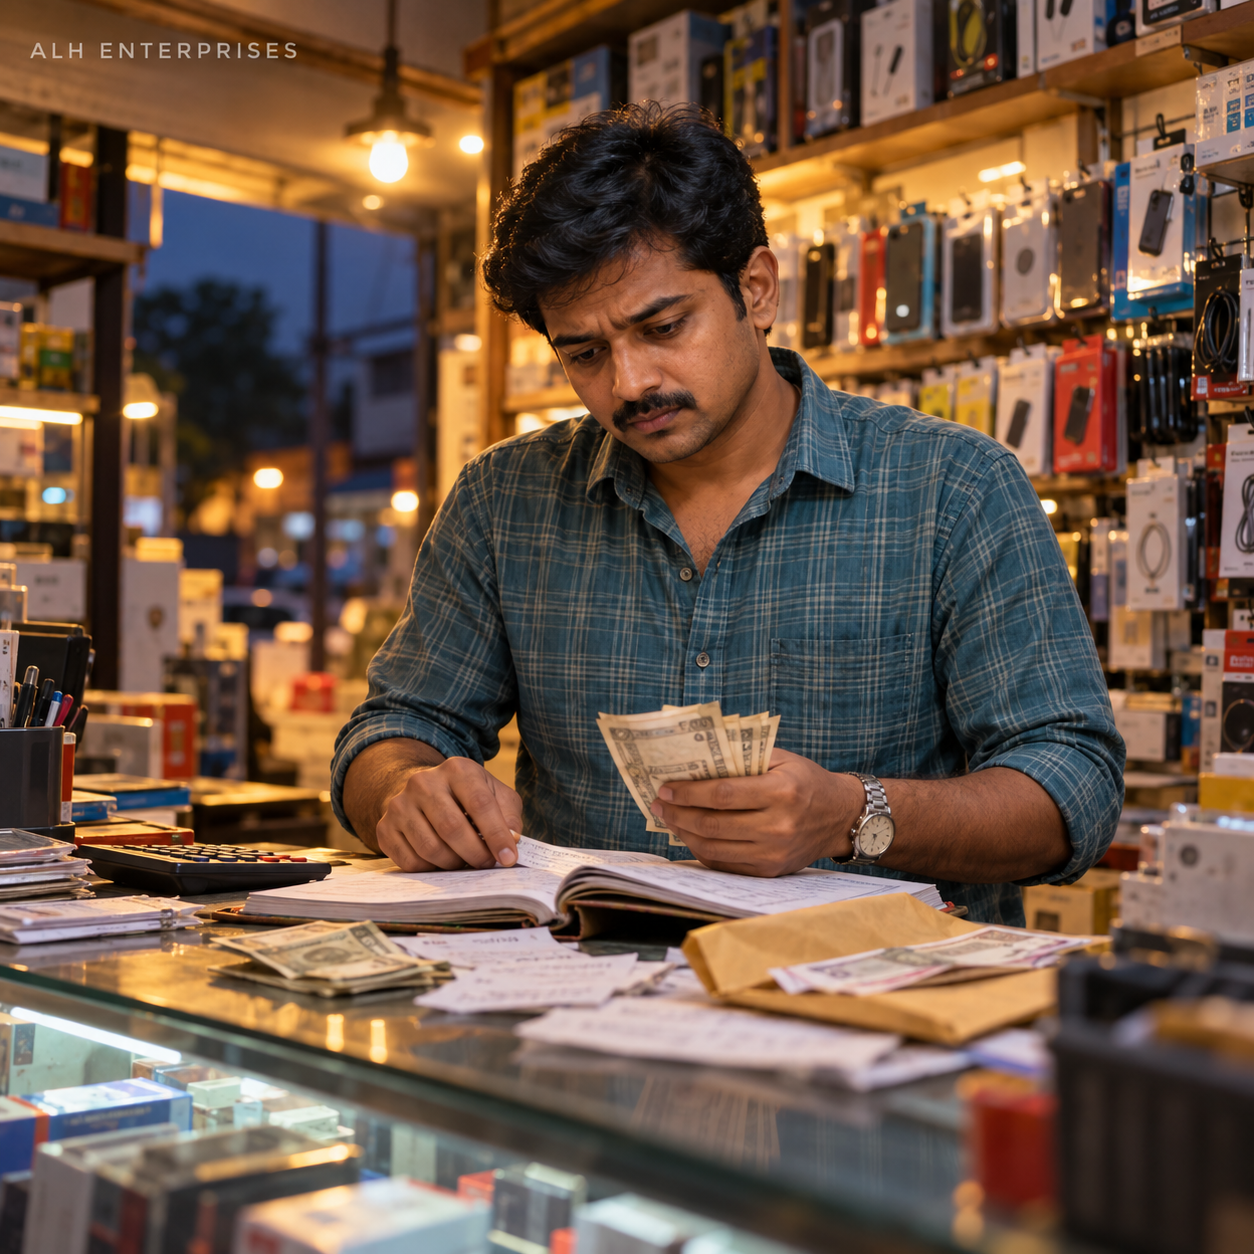
భీమవరం దగ్గర ఒక చిన్న electronics shop నడిపే రవి. ఉదయం shutter తీసినప్పటి నుంచి రాత్రి cash tally చేసే వరకు అతని రోజు calls, customers, supplier messagesతో పరుగెడుతుంది. Business బాగానే తిరుగుతోంది. ఇంటికి కావాల్సినవి వస్తున్నాయి. కానీ ప్రతి నెల చివరి మూడు రోజులు మాత్రం ఒకే scene.
Shop rent పోయింది. Supplier payment పోయింది. ఇంటి ఖర్చులు, school fee, EMI—అన్నీ వెళ్లిపోయాయి. “ఈసారి ఖచ్చితంగా save చేస్తాను” అనుకున్న రవి ledger మూసే సమయానికి, savings column మళ్లీ ఖాళీ. సమస్య అతను సంపాదించకపోవడం కాదు. వచ్చిన డబ్బులో ప్రతి రూపాయికి పని ఉంది—కానీ future Raviకి మాత్రం పని కేటాయించలేదు.
Pay Yourself First అంటే మీకే salary ఇవ్వడమా?
సులభంగా చెప్పాలంటే: income వచ్చిన వెంటనే, ఖర్చులు మొదలయ్యే ముందు, ముందే నిర్ణయించిన చిన్న మొత్తాన్ని savings లేదా long-term goal కోసం పక్కన పెట్టడం. ఇది “నాకు నచ్చినది వెంటనే కొనుక్కోవాలి” అనే permission కాదు. మీ భవిష్యత్తును కూడా ఒక తప్పనిసరి payeeగా చూడటం.
ఈ ideaని ఒక్కరే invent చేశారని చెప్పడం సరికాదు. కానీ George S. Clason రాసిన The Richest Man in Babylonలో “మన earningలో ఒక భాగం మన దగ్గర ఉండాలి” అనే principle ప్రసిద్ధి చెందింది. ఆ కథలు ancient Babylonలో జరిగిన నిజ చరిత్ర కాదు; modern financial parables. కాబట్టి lessonని తీసుకోవచ్చు—settingని historical proofగా చూడకూడదు.
ఆ bookలో one-tenth అనే example కనిపిస్తుంది. దాన్ని universal ruleగా తీసుకోవాల్సిన అవసరం లేదు. ఒక కుటుంబానికి 10% comfortable కావచ్చు; ఇంకొకరికి medical expenses, debt లేదా seasonal income వల్ల అది ప్రస్తుతం సాధ్యం కాకపోవచ్చు. Habit నిలబడటమే first win. ₹100తో మొదలైందా, 1%తో మొదలైందా అన్నదానికంటే, ఎందుకు పక్కన పెడుతున్నాం మరియు ఎప్పుడు review చేస్తాం అన్న clarity ముఖ్యం.
రవి పెద్ద percentageతో మొదలు పెట్టలేదు. తన uneven business cash flow చూసి, ప్రతి collection dayలో ఒక చిన్న, sustainable shareను separate accountకి move చేయాలని నిర్ణయించాడు. Fixed salary ఉన్నవారు payday transfer పెట్టుకోవచ్చు; variable income ఉన్నవారు ప్రతి receiptలో percentage లేదా weekly minimum ఎంచుకోవచ్చు.
Willpower కాదు—ఒక చిన్న system
మొదటి నెల రవి transfer చేతితో చేశాడు. రెండో నెల calendar reminder పెట్టాడు. తర్వాత predictable collection daysకి recurring transfer set చేశాడు. U.S. Consumer Financial Protection Bureau guidance కూడా automatic recurring transfers savingsని consistentగా చేయడానికి సులభమైన మార్గాల్లో ఒకటని చెబుతుంది. అయితే balance తక్కువగా ఉన్నప్పుడు overdraft లేదా failed transfer రాకుండా amount, dateని review చేయాలని అదే guidance హెచ్చరిస్తుంది.
Business ownerకి ఇంకొక confusion ఉంటుంది: shopలో ఉన్న cash అంతా తన personal income అనిపించడం. కానీ stock replacement, rent, tax, staff payment కోసం ఉన్న money కూడా అదే drawerలో ఉండొచ్చు. అందుకే రవి ముందుగా business obligations జాబితా చేశాడు. వాటిని దాటవేసి personal savingsకి పంపలేదు. Owner draw లేదా నిజంగా తీసుకోగల earning ఏదో తెలిసిన తర్వాతే తన “first” amount నిర్ణయించాడు. Pay yourself first అనేది suppliersని lastకి నెట్టడం కాదు; personal futureని planలో కనిపించేలా చేయడం.
అందుకే automationకి ముందు రవి మూడు rules రాసుకున్నాడు:
- Small enough to continue: cash flowని గాయపరచని మొత్తంతో మొదలు.
- Separate enough to protect: daily-spend accountకి కనిపించకుండా వేరుగా ఉంచడం.
- Visible enough to review: నెలకు ఒకసారి balance, upcoming bills, goalను చూడడం.
Saving automatic కావచ్చు; judgment automatic కాకూడదు. High-interest debt, overdue essentials, unstable income ఉన్నప్పుడు ఒక generic percentage అందరికీ సరిపోదు. అవసరమైతే qualified financial professionalతో మీ పరిస్థితికి సరిపోయే order నిర్ణయించాలి.
మరో practical rule: savings accountకి పేరు పెట్టడం. “Savings” అనే vague labelకన్నా “Emergency buffer—shop & home” వంటి purpose temptationని తగ్గించవచ్చు. Goalకు date లేదా first milestone పెట్టండి. ₹5,000 చేరిన తర్వాత amount review చేయడం, seasonal low-income monthలో transfer తగ్గించడం, business cash flow తిరిగి stable అయినప్పుడు పెంచడం—ఇవి failure కాదు. ఇవే system maintenance.
ఒక repair bill వచ్చింది. ఈసారి panic రాలేదు.
కొన్ని నెలల తర్వాత shopలో ఒక shelf, wiring repair అవసరమైంది. ముందైతే supplier payment వాయిదా వేయడం లేదా personal card వాడడం జరిగేది. ఈసారి రవి దగ్గర ఒక modest buffer ఉంది. మొత్తం సమస్య solve అయిపోయిందని కాదు; కానీ decision తీసుకోవడానికి breathing space వచ్చింది.
Emergency savings ఉద్దేశం “ఏం జరిగినా సరిపడే పెద్ద number” చూపించడం కాదు. Unexpected expense వచ్చినప్పుడు మరో ఖరీదైన సమస్యను సృష్టించకుండా ఉండేందుకు మొదటి cushion ఇవ్వడం. Consumer guidance కూడా dedicated emergency fundను basic protectionగా సూచిస్తుంది. ఎంత fund అవసరమో household, business obligations, income stabilityపై ఆధారపడుతుంది.
ఆ repair రోజున రవికి వచ్చిన పెద్ద మార్పు bank balanceలో మాత్రమే కాదు. Customer ముందు tension చూపాల్సిన అవసరం తగ్గింది. ఇంటికి వెళ్లి “ఇప్పుడు ఏ bill ఆపాలి?” అనే emergency discussion కూడా రాలేదు. Money habit యొక్క value చాలా సార్లు interest figureలో కనిపించే ముందు, మన conversationsలో కనిపిస్తుంది: తక్కువ panic, స్పష్టమైన options, deliberate decisions.
ఈ నెల మీ Pay Yourself First habit ఇలా మొదలు పెట్టండి
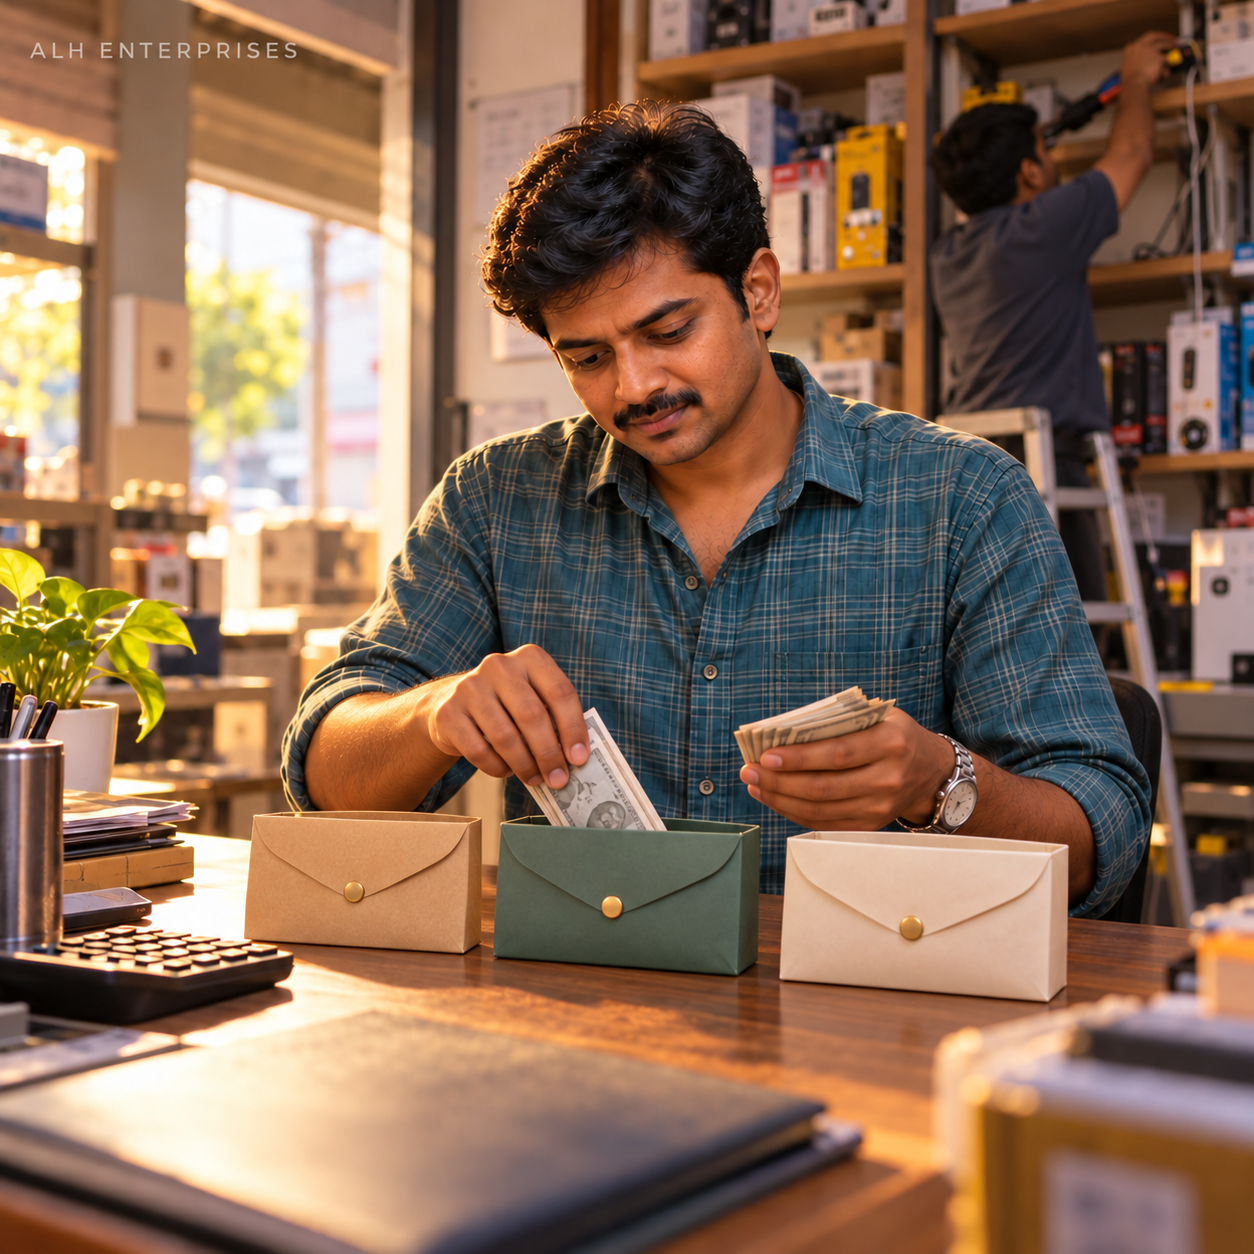
- ఒక purpose ఎంచుకోండి. Emergency buffer, annual fee, business reserve—మొదట ఒకటే.
- Realistic amount నిర్ణయించండి. Perfect 10% కోసం ఆగకుండా, మీరు కొనసాగించగల చిన్న amount లేదా percentageతో మొదలు పెట్టండి.
- Incomeకి దగ్గరగా trigger పెట్టండి. Salary day, weekly collections day లేదా ప్రతి major receipt తర్వాత.
- Separate place ఇవ్వండి. Goalకి సరిపోయే safe savings optionను fees, access rules తెలుసుకుని ఎంచుకోండి.
- 30 రోజుల తర్వాత review చేయండి. Essentials miss అయ్యాయా? Transfer నిలిచిందా? Amount పెంచాలా, తగ్గించాలా?
రవి కథలో నిజమైన turning point ఎక్కువ income కాదు. “ఈసారి ఏమైనా మిగులుతుందేమో” అనే hopeని, “ముందే ఒక చిన్న భాగం పక్కన పెడతాను” అనే processగా మార్చడం.
ఒక చిన్న ప్రశ్న
మీ ఆదాయం వచ్చిన రోజే, future-youకి ఎంత పంపగలరు?
చిన్న amount. Clear purpose. Repeatable date. అక్కడే habit మొదలవుతుంది.
Sources & fact-check notes
- Consumer Financial Protection Bureau: emergency funds and automatic recurring transfers
- Investor.gov: paying yourself first through automatic contributions
- George S. Clason text: “a part of all I earned was mine to keep”
Educational content only; not individualized financial, investment, tax or legal advice. Ravi’s amounts and results are intentionally not quantified because the example is fictional.